On 13 October 2026, Indonesia's Financial Services Authority brought Real World Asset tokenisation into its Digital Financial Literacy programme. OJK describes RWA tokenisation as the digital representation of a real asset or economic rights connected with that asset using digital technology, including distributed ledger technology.
The phrase “asset or economic rights” matters.
When property, gold, securities or another asset is tokenised, the first question should not be:
“How much is one token?”
A more fundamental question is:
“What rights does this token actually give its holder?”
A Token Is a Representation
The BIS and Committee on Payments and Market Infrastructures describe tokenisation as generating and recording digital representations of traditional assets on programmable platforms. Tokens can combine information about an asset or claim with rules governing how it may be transferred.
That technology can make transfers and settlement more programmable.
It does not remove the economic substance underneath.
A gold token needs a reliable relationship with the gold.
A token representing property-related economic benefits requires a legal structure defining those benefits.
A token involving securities needs clarity around cash flows, issuer obligations, custody, transfer and settlement.
Digital representation is not automatically the same thing as direct ownership.
Indonesia Is Already Testing Different Structures
OJK's regulatory sandbox demonstrates why RWA tokenisation should not be viewed as one uniform model.
By September 2026, sandbox graduates included models involving gold tokenisation, securities tokenisation under a Fund Management Contract structure, and tokenisation of property ownership benefits.
Their operational structures also differ.
OJK notes that the gold-tokenisation model works with Pegadaian to safeguard physical gold underlying the tokens, while the securities-tokenisation model involves investment managers and custodian banks.
For the property-benefit model, OJK has described separate entities performing the token-trading platform function and the role of property owner and custodian.
All are forms of tokenisation.
They are not the same legal or operational architecture.
Start with Rights, Not Blockchain
Imagine a property worth IDR10 billion being represented economically by 10,000 tokens.
That statement is still incomplete.
Does each token convey direct legal title to a fraction of the property?
Does it represent a contractual economic interest in a vehicle that owns the asset?
Does the holder receive rental income?
Sale proceeds?
Voting rights?
Who pays maintenance expenses?
What happens if the issuer or platform becomes insolvent?
Those answers may matter more than the name of the blockchain.
Technology determines how the record and transfer operate.
Legal and economic architecture determines what is actually being transferred.
A Useful Principle from Basel
The Basel Framework provides a clear prudential example for tokenised traditional assets.
For certain tokenised assets to receive treatment comparable with their traditional form, they must confer equivalent legal rights—for example rights to cash flows and insolvency claims for financial instruments, or legal rights comparable with traditional ownership records for physical commodities.
The framework also notes that the condition is not met when the digital asset must first be redeemed or converted before the holder receives equivalent legal rights, or when its structure introduces additional counterparty credit risk.
These are banking prudential rules, not Indonesian retail-token rules.
But the principle creates an excellent question:
Does the token itself deliver the rights being advertised, or merely provide a route to another party expected to provide those rights later?
Custody Is Still Part of the System
Underlying assets have to exist somewhere.
Gold requires physical custody.
Securities need registries and custody systems.
Property has legal title and physical administration.
Tokenisation adds another digital layer.
The system therefore needs a trustworthy link between off-chain reality and on-chain representation.
What happens when the token registry says one thing and the custody records say another?
How are changes in the underlying asset reflected digitally?
Who resolves errors?
How are income and corporate actions distributed?
BIS analysis makes clear that programmable platforms still require governance, legal frameworks, custody, risk management and operational controls.
Intermediaries may change roles.
They do not necessarily disappear.
Fractionalisation Does Not Improve Asset Quality
One widely discussed benefit is fractionalisation.
A large asset can be represented through smaller economic units, potentially reducing the minimum investment size.
OJK identifies possible benefits including transactional efficiency, broader access to financial instruments and alternative financing.
Fractionalisation, however, changes the ticket size.
It does not automatically change the quality of the underlying economics.
A poorly performing property remains poorly performing.
A difficult-to-verify commodity still needs assurance.
A weak issuer does not become financially strong because the claim is recorded on a blockchain.
A token can divide a claim more efficiently.
It does not necessarily make the claim better.
Liquidity Is Not Automatic Either
Tokenisation is frequently associated with better liquidity.
Smaller units and digital transfer can indeed lower some barriers.
A transferable token, however, still needs a buyer.
BIS research on tokenised real estate found evidence that tokenisation can help preserve liquidity under particular conditions, but the liquidity effect in its dataset depended importantly on platform buyback arrangements. Those arrangements also introduced higher platform insolvency risk.
The lesson is important:
Liquidity has an architecture and a cost.
A digital marketplace does not automatically have market depth.
Fractionalisation does not automatically create price discovery.
Transferability does not guarantee demand.
Tokenisation Is Broader Than Crypto Speculation
RWA tokenisation often uses technologies associated with crypto markets, particularly DLT.
Its economic concept is broader.
BIS describes tokenisation as digital representation of money, financial claims and real assets on programmable platforms, allowing functions such as programmability and more integrated settlement.
The analytical question therefore should not begin with:
“Will the token price rise?”
It should begin with the underlying asset, rights, issuer or vehicle, custody, cash flows, redemption arrangements, platform risks and real secondary-market structure.
From the Asset to the Token—and Back Again
As a GATICORP editorial framework:
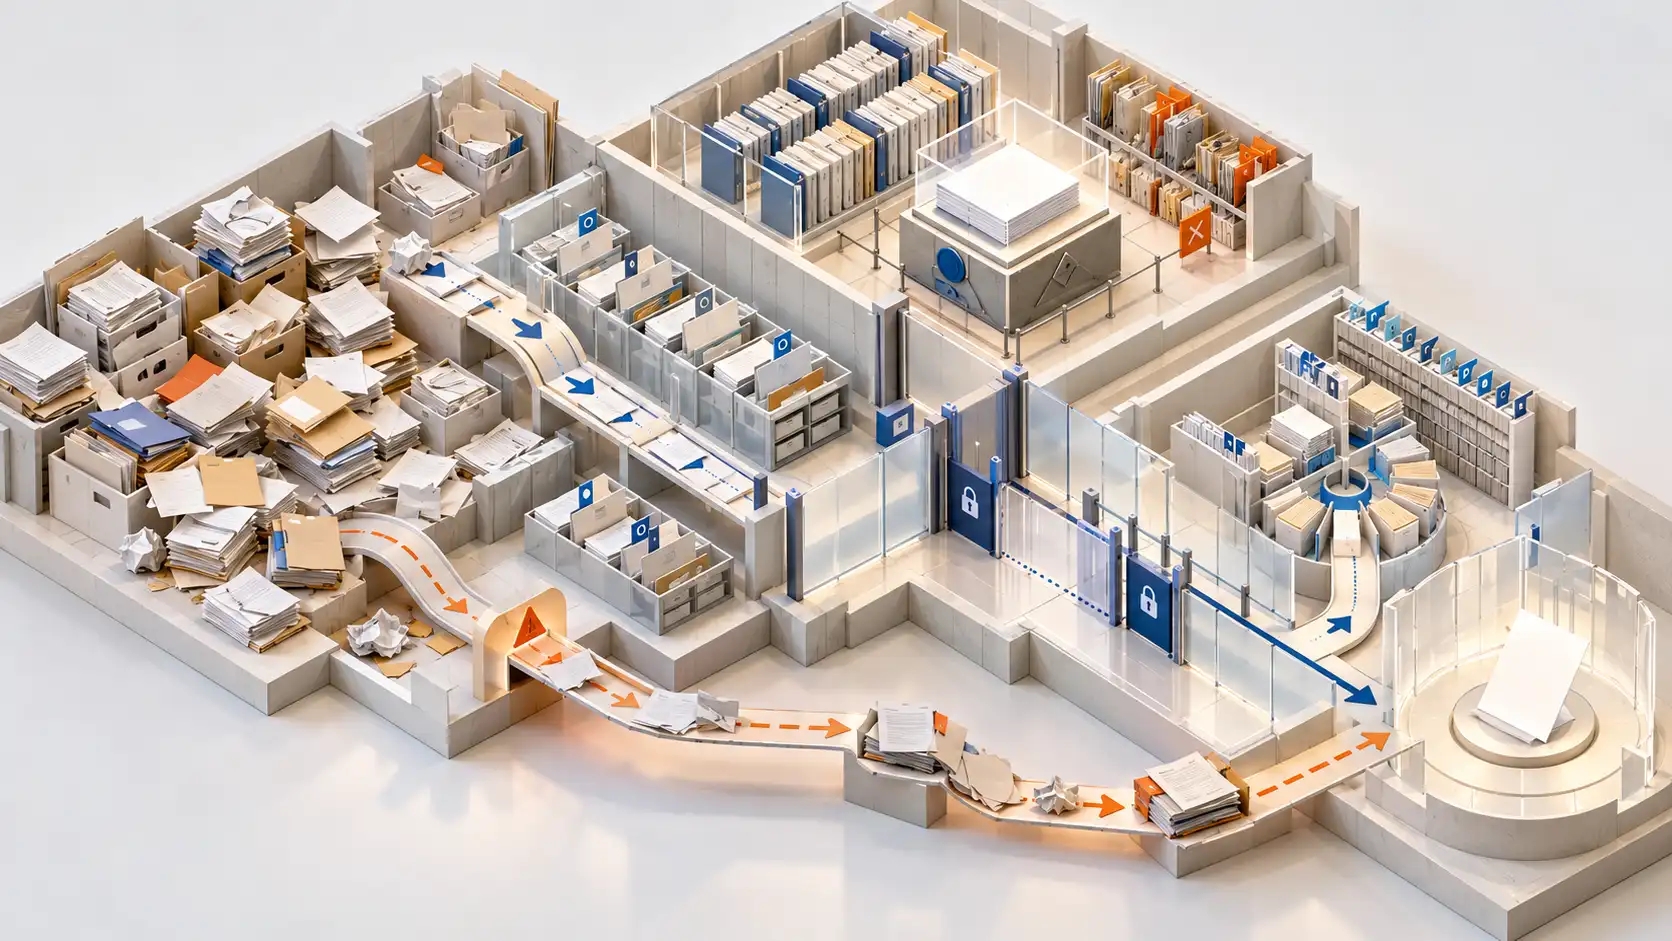
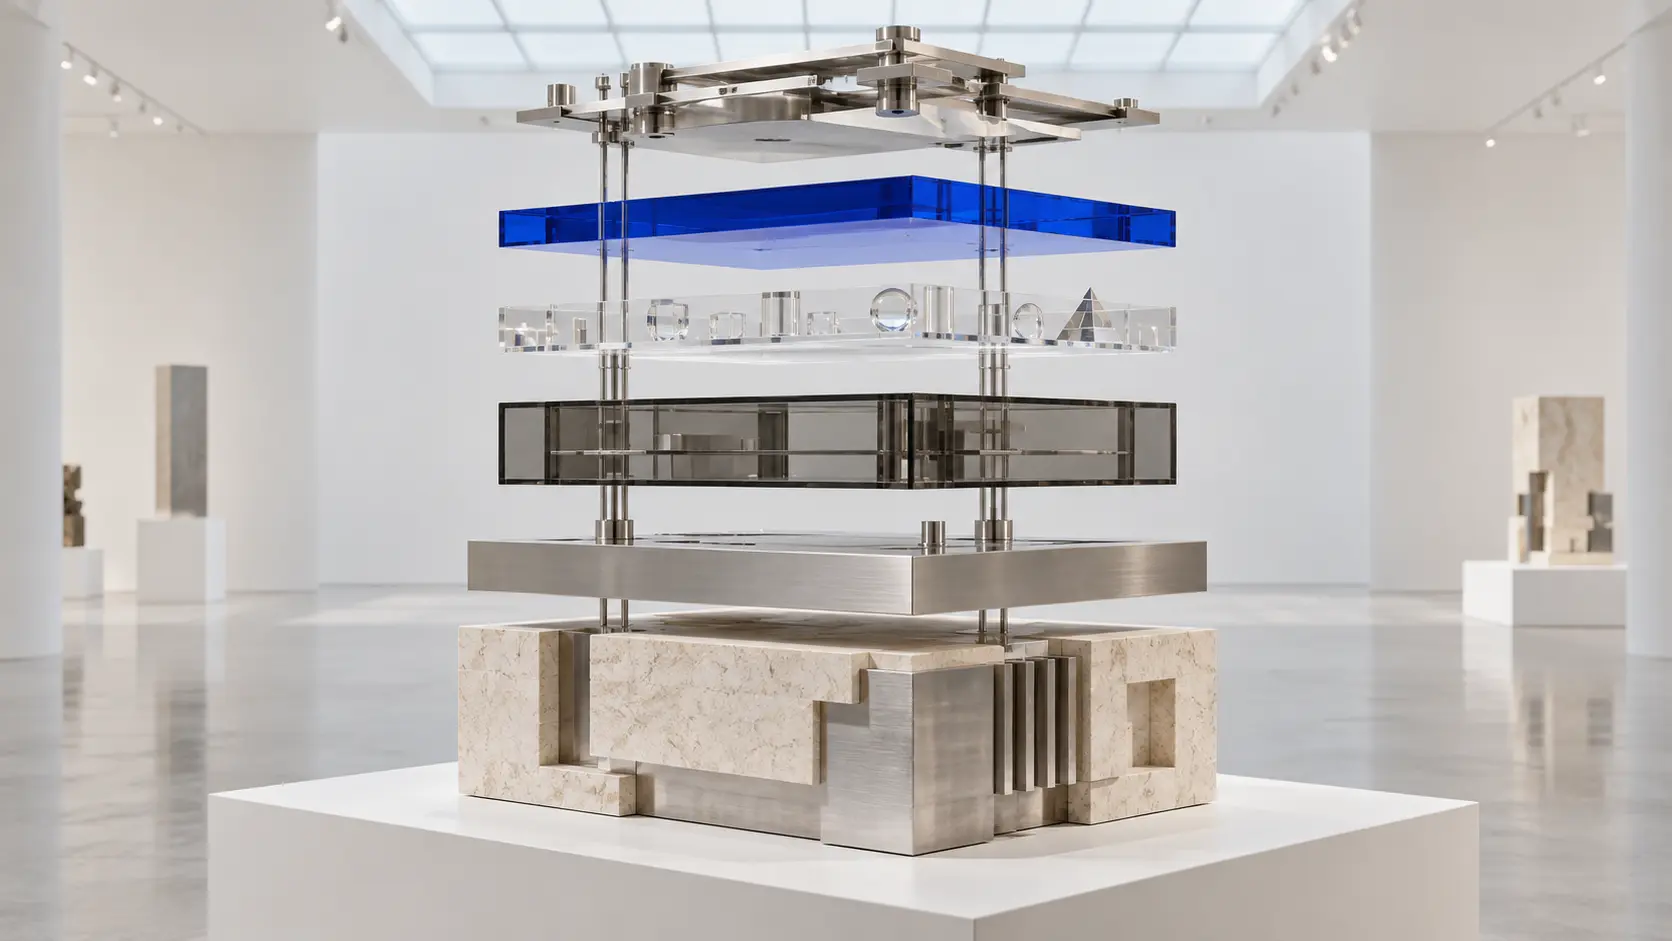
Underlying Asset → Legal / Economic Right → Issuer / Vehicle → Registry & Custody → Token → Transfer & Settlement → Cash Flow / Redemption
The framework deliberately places the token in the middle rather than at the beginning.
The underlying asset creates economic substance.
Rights explain what the holder actually owns or can claim.
The issuer or legal vehicle connects those rights with the token holder.
Registry and custody maintain the underlying record.
The token provides the digital representation.
Transfer and settlement move the claim.
Cash flow or redemption is where economic value eventually reaches the holder.
This is not an official OJK or BIS classification.
It is a way to move from digital interface back to economic reality.
Do Not Start with the Token
Tokenisation has real potential.
Indonesia has already tested several RWA structures through OJK's regulatory sandbox, and OJK is now actively promoting literacy about both the opportunities and risks. At the same time, the regulator emphasises legal certainty over underlying assets, information transparency, technology security, governance and clarity around the rights and obligations of token holders.
That is the part easily lost when discussions begin with blockchain.
Technology can change how a claim is recorded.
It can change how it is transferred.
It can reduce certain frictions.
It can make transactions programmable.
What it cannot do automatically is repair a poor underlying asset, ambiguous legal rights, weak custody or unclear governance simply by placing them behind a digital token.
Before buying or building an RWA token, the most useful first question may therefore be:
What exactly does the person holding this token own?
- OJK, 13 October 2026 — Digital Financial Literacy 2026 on RWA Tokenisation. Used for the Indonesian definition, potential benefits and OJK's emphasis on legal certainty, governance, security, transparency, economic rights and consumer protection.
- OJK — 2026 Regulatory Sandbox Reporting. Used for gold, securities and property-benefit tokenisation models and their different custody and institutional arrangements. Passing the sandbox does not mean a product is risk-free or automatically satisfies every other applicable licensing requirement.
- BIS/CPMI — Tokenisation in the Context of Money and Other Assets. Used for definitions, programmable platforms and the importance of governance, legal frameworks, custody, liquidity and operational risk.
- Basel Committee — Basel Framework: Cryptoasset Exposures. Used only as a prudential illustration of equivalent legal rights for certain tokenised traditional assets. It is not Indonesian retail-token regulation.
- BIS Working Paper 1311 — When Bricks Meet Bytes. Used for the liquidity discussion and the finding that particular liquidity benefits in tokenised real-estate markets can depend on platform design and bring additional trade-offs.
- Editorial note: this article is educational rather than investment advice or a legal interpretation of any specific token. Underlying Asset → Legal / Economic Right → Issuer / Vehicle → Registry & Custody → Token → Transfer & Settlement → Cash Flow / Redemption is a GATICORP editorial framework.
Published: October 22, 2026