In September 2026, Indonesia's Financial Services Authority said it was examining 15 entities suspected of conducting insurance or reinsurance brokerage activities without authorisation. OJK said the cases remained at the evidence-gathering and evidence-strengthening stage and that the number could increase as regulators traced additional sources of business.
Several months earlier, OJK had introduced QR codes on registered insurance and reinsurance brokers' registration certificates to make verification easier. As of 31 March 2026, OJK reported 560 registered insurance brokers and 105 registered reinsurance brokers holding STTD registration.
Those developments matter.
But the first question for a business buyer should not only be:
“Is this broker properly registered?”
There is another question to understand first:
“Who is actually representing whom?”
Broker, Agent and Insurer Are Different Positions
Under Indonesia's Insurance Law, an insurance broker is a qualified person working for an insurance brokerage company who can recommend or represent policyholders, insureds or participants in insurance placement and/or claim settlement.
An insurance agent occupies a different position. The agent acts for and on behalf of an insurer or sharia insurer in marketing its products.
OJK also defines an insurance brokerage company as an intermediary in insurance placement and claim settlement that acts in the interests of the insured.
The distinction is not about which role is inherently better.
Each serves a different function.
The important point for a buyer is understanding the representation before making a purchase decision.
Buyers Need More Than Three Quotations
In the simplest view, a broker appears to collect three insurance quotations.
Insurer A costs this much.
Insurer B is cheaper.
Insurer C has a different deductible.
If that is all the buyer sees, the broker's value can look like simple price comparison.
Corporate insurance is often more complicated.
Before asking the market for quotations, the company's risk has to be described. Asset values need to be accurate. Business activity needs to be clear. Claims history may matter. Property, liability, cargo, engineering, catastrophe, cyber or business-interruption exposures can each demand different information.
OJK educational material describes brokerage workflow as including formal appointment, preparation of quotation slips, translating the insured's requirements for insurers, proposals, placement summaries, checking that policy documents match placement instructions, and managing documentation.
Before price comparison comes another task:
making the risk understandable to the market.
Risk Information Shapes Placement Quality
Insurance is not simply a case of buying an identical product from different shops.
Insurers can have different appetite, capacity, underwriting requirements, wording, deductibles, exclusions, sublimits and conditions.
Submission quality therefore matters.
If a risk is described too broadly, quotations may not be truly comparable.
One insurer may price on one assumption while another receives a more complete picture of the exposure.
The premiums look comparable.
The underlying offers may not be.
A capable broker can help reduce that mismatch by ensuring the buyer's risk and the insurance market communicate through sufficiently clear information.
The Cheapest Premium May Hide Wording Differences
Corporate buyers often receive comparison sheets.
Premium columns are easy to read.
Policy wording is harder.
Yet several lines of wording can materially change the protection when a loss occurs.
Limits can appear equal while sublimits differ.
Headline coverage can sound similar despite different exclusions.
Deductible structures can vary.
An extension may be available from one insurer and absent from another.
Conditions or warranties may affect how coverage operates.
A useful comparison therefore goes beyond premium.
It asks what each policy actually promises.
The broker does not eliminate the buyer's own responsibility to understand its decision, and complex arrangements may still require legal, technical or specialist review.
Advisory value comes from translating differences into business consequences rather than merely displaying numbers.
The Mandate Matters
Broker value also depends on the mandate.
Is the broker responsible for the entire insurance programme?
One line of business?
Placement only?
Renewal remarketing?
Claims administration?
May the broker approach the whole market or only selected insurers?
What information may be disclosed?
Who within the buyer organisation has authority to instruct the broker?
OJK educational material describes the use of a formal appointment letter defining the scope of the relationship.
Representation does not mean unlimited authority.
It operates within the agreed mandate, regulations, contracts and instructions.
The Broker's Role Can Continue After Policy Issuance
One of the most visible functions emerges when a claim occurs.
OJK Regulation 70/2016 sets obligations for brokerage companies to assist policyholders and insureds with claim requirements. These include initial notification, information about supporting documents, transmission of documents to the insurer, assistance in obtaining claim-status information, and communication of the claim amount approved by the insurer.
The distinction needs to remain clear.
The broker supports the process.
The broker does not automatically determine that every claim must be paid.
The insurer still evaluates a claim according to policy wording, facts, coverage, exclusions, conditions, documentation and applicable rules.
A good broker should not promise an outcome it cannot control.
Its value is helping the claim move through the process with clear, accurate and traceable information.
The Insurer Still Carries the Insurance Risk
Using a broker does not change the fundamental structure of the insurance contract.
The policy remains the insurance agreement involving the insurer as risk carrier, while brokers operate as supporting intermediaries.
That distinction matters because buyers may have a closer working relationship with a broker than with the insurance company itself.
The insurer remains responsible for the insured risk according to the policy.
The broker sits between the risk owner and the market.
That intermediary role can be highly valuable without replacing the insurer.
Registration Is Now Easier to Check
On 4 May 2026, OJK introduced QR codes for insurance and reinsurance broker registration certificates. The regulator said the mechanism allows faster, easier and real-time verification of identity and registration status while reducing the risk of dealing with unregistered parties.
OJK links the registration framework with Indonesia's Financial Sector Development and Strengthening Law and OJK Regulation No. 24 of 2023 governing the licensing and institutional framework for insurance brokers, reinsurance brokers and loss adjusters.
For a corporate buyer, this makes one basic due-diligence check easier.
Valid registration is still only a baseline.
The buyer must then assess competence, experience, service capability, responsiveness, market knowledge, governance and suitability for the risks involved.
Being licensed does not automatically mean being excellent.
Operating without the necessary authorisation is a much more fundamental concern.
Read the Relationship from Risk Owner to Claim
As a GATICORP editorial framework:
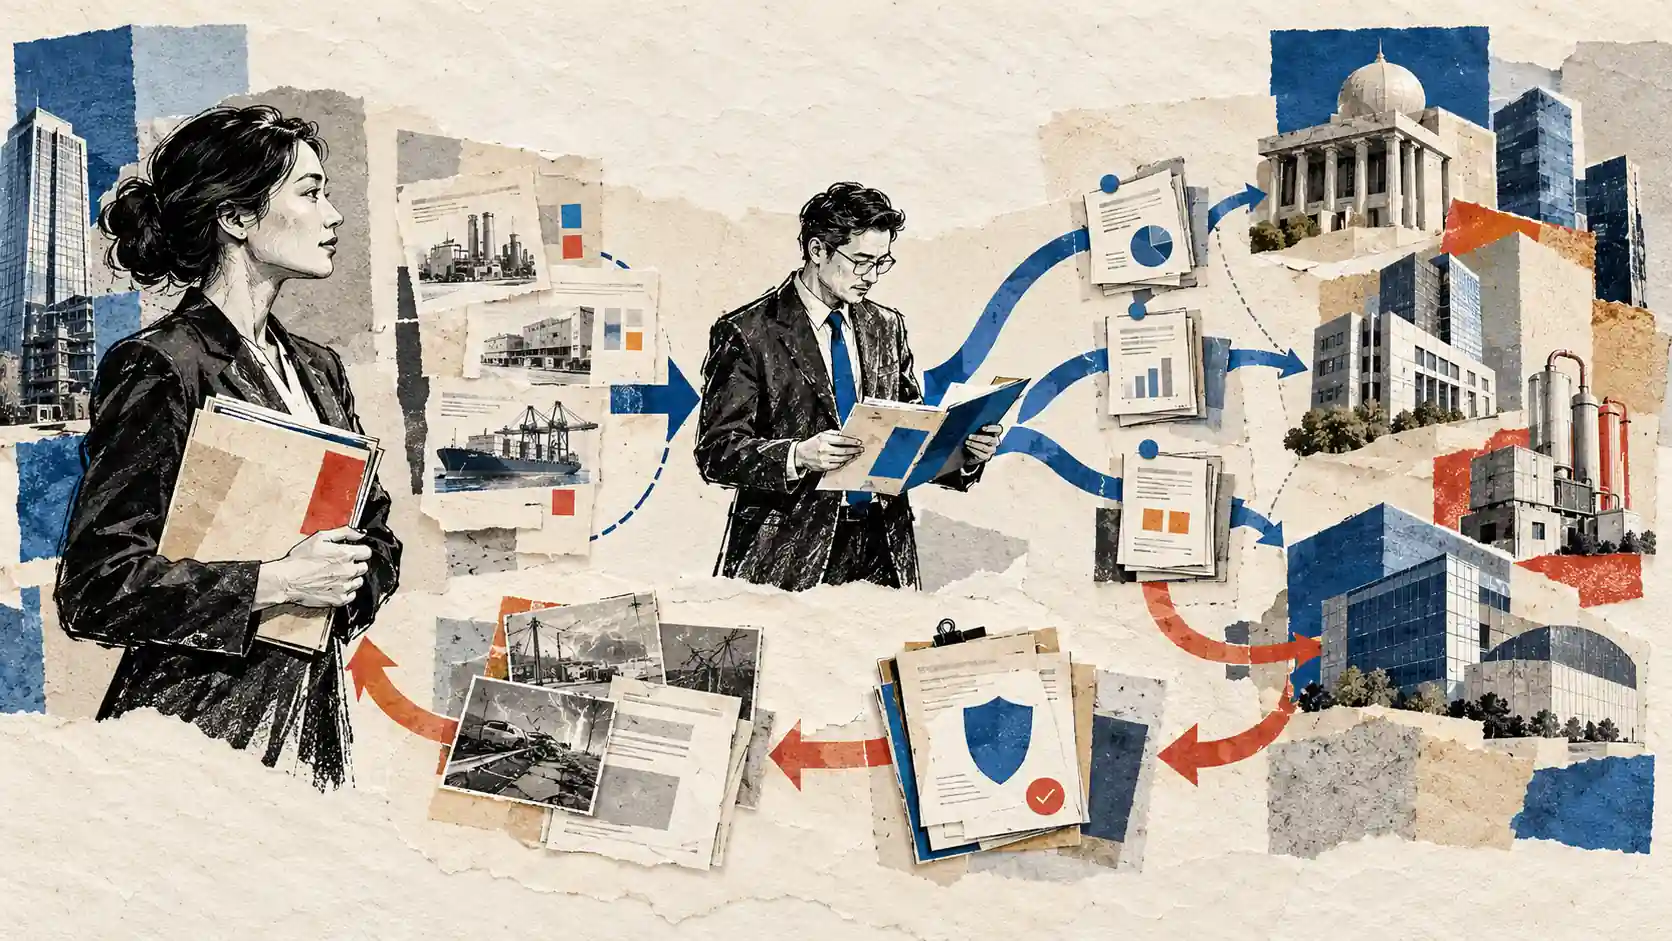
Risk Owner → Broker Mandate → Risk Information → Insurance Market → Placement → Policy → Claim Support
The Risk Owner understands the exposure requiring protection.
The Broker Mandate defines representation and scope.
Risk Information translates the exposure into something insurers can assess.
The Insurance Market supplies appetite, capacity, terms and pricing.
Placement turns the selected structure into an insurance arrangement.
The Policy becomes the contractual wording.
Claim Support helps the insured navigate the process when an insured event occurs.
This is not a mandatory OJK workflow and not every placement follows an identical sequence.
Its purpose is to show why a broker is more than a price-search mechanism.
The Better Question Is Not Simply “Who Is Cheapest?”
For straightforward insurance needs, price comparison can feel efficient.
For complex corporate risks, price is only one part of the decision.
Business owners should understand who represents them, how their risk is presented to the market, whether proposals are genuinely comparable, how wording is reviewed, who manages documentation, and what happens when a claim begins.
The intermediary's value is therefore not merely carrying insurer quotations to the buyer.
Its deeper role is helping ensure that the buyer's risk is correctly understood by the insurance market.
Before selecting the policy, ask:
Who represents our interests—and do we understand the mandate we have given them?
- OJK — September 2026 Board of Commissioners Meeting. Used for the 15 entities being examined for suspected unlicensed insurance/reinsurance brokerage activities. OJK had not declared those entities guilty; the process remained in evidence gathering and strengthening.
- OJK, 4 May 2026 — QR Code Registration for Insurance and Reinsurance Brokers. Used for the registration-verification mechanism and the reported 560 insurance brokers and 105 reinsurance brokers with STTD registration as of 31 March 2026.
- Indonesia Insurance Law No. 40 of 2014 within the sector's current framework following the P2SK reforms. Used for the distinction between insurance brokers representing policyholders/insureds and insurance agents acting for insurers.
- OJK — Insurance Supporting Services. Used for the definition of an insurance brokerage company acting in the interest of the insured.
- OJK Regulation 70/POJK.05/2016 as amended by OJK Regulation 28 of 2022. Used specifically for brokerage obligations in assisting the claim-submission and claim-status process.
- OJK Regulation No. 24 of 2023. Used for the current licensing and institutional context governing insurance brokerage companies.
- OJK Insurance Education Material. Used as an educational description of appointment letters, quotation and placement slips, proposals, policy-document checks and brokerage workflow. It is not treated as a substitute for binding regulation or policy wording.
- Editorial note: this article does not state that brokers guarantee claim payment or that all brokers provide identical services. Claims remain governed by policy coverage, facts, exclusions, conditions, documentation and the insurer's assessment under applicable rules. Risk Owner → Broker Mandate → Risk Information → Insurance Market → Placement → Policy → Claim Support is a GATICORP editorial framework.
Published: October 20, 2026