As of August 2026, Indonesia's Financial Services Authority reported accumulated general insurance and reinsurance premium income of IDR99.61 trillion, down 2.35% year on year. Aggregate Risk-Based Capital for the sector stood at 331.52%, well above the 120% regulatory threshold.
Those numbers need careful interpretation.
A decline in premium income does not prove that Indonesian insurance rates have fallen. Premium income can change because of business volume, portfolio mix, insured values, timing, exposures, rates, or several of those factors at once.
That creates an important distinction:
premium volume is not pricing adequacy.
Price and Risk Do Not Move Together
The price of a policy can change from one renewal to the next.
Physical risk does not have to follow.
A warehouse can still burn during a competitive insurance market. Vehicle repair costs can rise while motor rates soften. Reconstruction values can increase even when a property policy becomes cheaper.
Premium is the financial price of transferring risk.
Exposure is the underlying reality.
The relationship between the two has to be continuously tested.
Premium Volume Is Not the Same as Rate
Suppose an insurer covers 1,000 vehicles at an average premium of IDR5 million.
Premium volume is approximately IDR5 billion.
The following year, average premium falls to IDR4.8 million, but the number of insured vehicles rises to 1,200.
Premium volume increases to IDR5.76 billion even though average pricing has fallen.
The opposite can also occur.
Premium income can contract even if rates remain unchanged when business volume, exposure or portfolio mix declines.
Headline premium growth therefore tells us little about pricing adequacy on its own.
Risk Has an Expected Cost
At a simplified level, insurance pricing needs to accommodate expected claims, operating and acquisition costs, reinsurance, uncertainty and the use of capital.
Policy terms then change the economics further.
A higher deductible alters expected insurer payments.
Different limits alter maximum exposure.
Sublimits restrict particular components of cover.
Exclusions determine which events sit outside the transfer.
Two quotations with different prices may therefore not represent exactly the same risk proposition.
Price has to be read together with terms.
Loss and Combined Ratios Help Explain Underwriting
Property and casualty insurers commonly look at loss ratios and combined ratios to assess technical performance.
The loss ratio connects incurred losses with premium. The expense ratio adds underwriting-related operating costs. The combined ratio brings the two together as a measure of underwriting performance before investment income. A figure above 100 generally indicates an underwriting loss; below 100 indicates an underwriting profit.
These measures are not perfect answers for every line or every period.
Catastrophes can create volatility. Long-tail claims develop differently. Reserve changes can affect results.
But they illustrate why premium growth alone is not the objective.
The underlying question is whether the premium collected is appropriate for the risk and loss costs being accepted.
A Softer Global Market Does Not Mean Lower Risk
Swiss Re expects global non-life real premium growth to reach a cyclical low of roughly 0.6% in 2026, with competitive pricing and ample capacity contributing to softer commercial and personal-lines pricing through 2026–27.
At the same time, Swiss Re points to renewed inflationary pressures on claims severity through repair, replacement and liability costs.
The observation should not be mechanically applied to Indonesia.
Local pricing depends on Indonesian loss experience, regulation, competition, reinsurance, capacity and portfolio conditions.
The global cycle nevertheless demonstrates a broader underwriting principle:
market pricing and loss costs can move at different speeds.
A Cheaper Renewal Is Not Automatically a Better Programme
Corporate buyers naturally pay attention to the renewal premium.
Last year: IDR1 billion.
This year: IDR850 million.
A 15% saving looks attractive.
But a fair comparison needs to ask what else changed.
Are insured values current?
Did deductibles rise?
Were limits or sublimits reduced?
Were new exclusions introduced?
Has the company's operation expanded?
Has inventory increased?
Have new locations been added?
Has a machinery investment changed business-interruption exposure?
A lower price for genuinely equivalent protection can be a strong outcome.
A lower price caused by materially reduced protection is a different proposition.
Underinsurance Can Develop Quietly
Consider a building with an estimated replacement cost of IDR100 billion when the original insurance programme was arranged.
Several years later, materials, labour and reconstruction costs increase the actual rebuilding requirement to IDR120 billion.
If the insured value remains unchanged, a gap has developed even though the building itself still looks the same.
The exact claim consequence depends on policy wording and structure.
From a risk-management perspective, however, the exposure has already moved.
Renewal should therefore not simply repeat last year's values.
The risk needs to be refreshed.
Capital and Pricing Answer Different Questions
The Indonesian general insurance and reinsurance sector's aggregate RBC of 331.52% indicates aggregate solvency remained above the regulatory threshold as of August 2026.
That does not make RBC a measure of pricing adequacy.
Solvency capital answers one question.
Whether a portfolio is being written at economically sustainable prices answers another.
Strong capital does not remove the need for underwriting discipline.
Good underwriting does not remove the need for sufficient capital.
They support resilience from different directions.
Price Is Only One Lever
When an exposure cannot be comfortably written at a particular price, insurers have more tools than simply increasing the premium or declining the account.
Deductibles can change.
Limits can change.
Sublimits can be introduced.
Risk engineering can improve the exposure.
Reinsurance can alter retained risk.
Coverage terms can be adjusted.
Underwriting is therefore a combination of risk selection, price, capacity, terms and loss-control information.
Premium is simply the most visible part.
From Exposure to Review
As a GATICORP editorial framework:
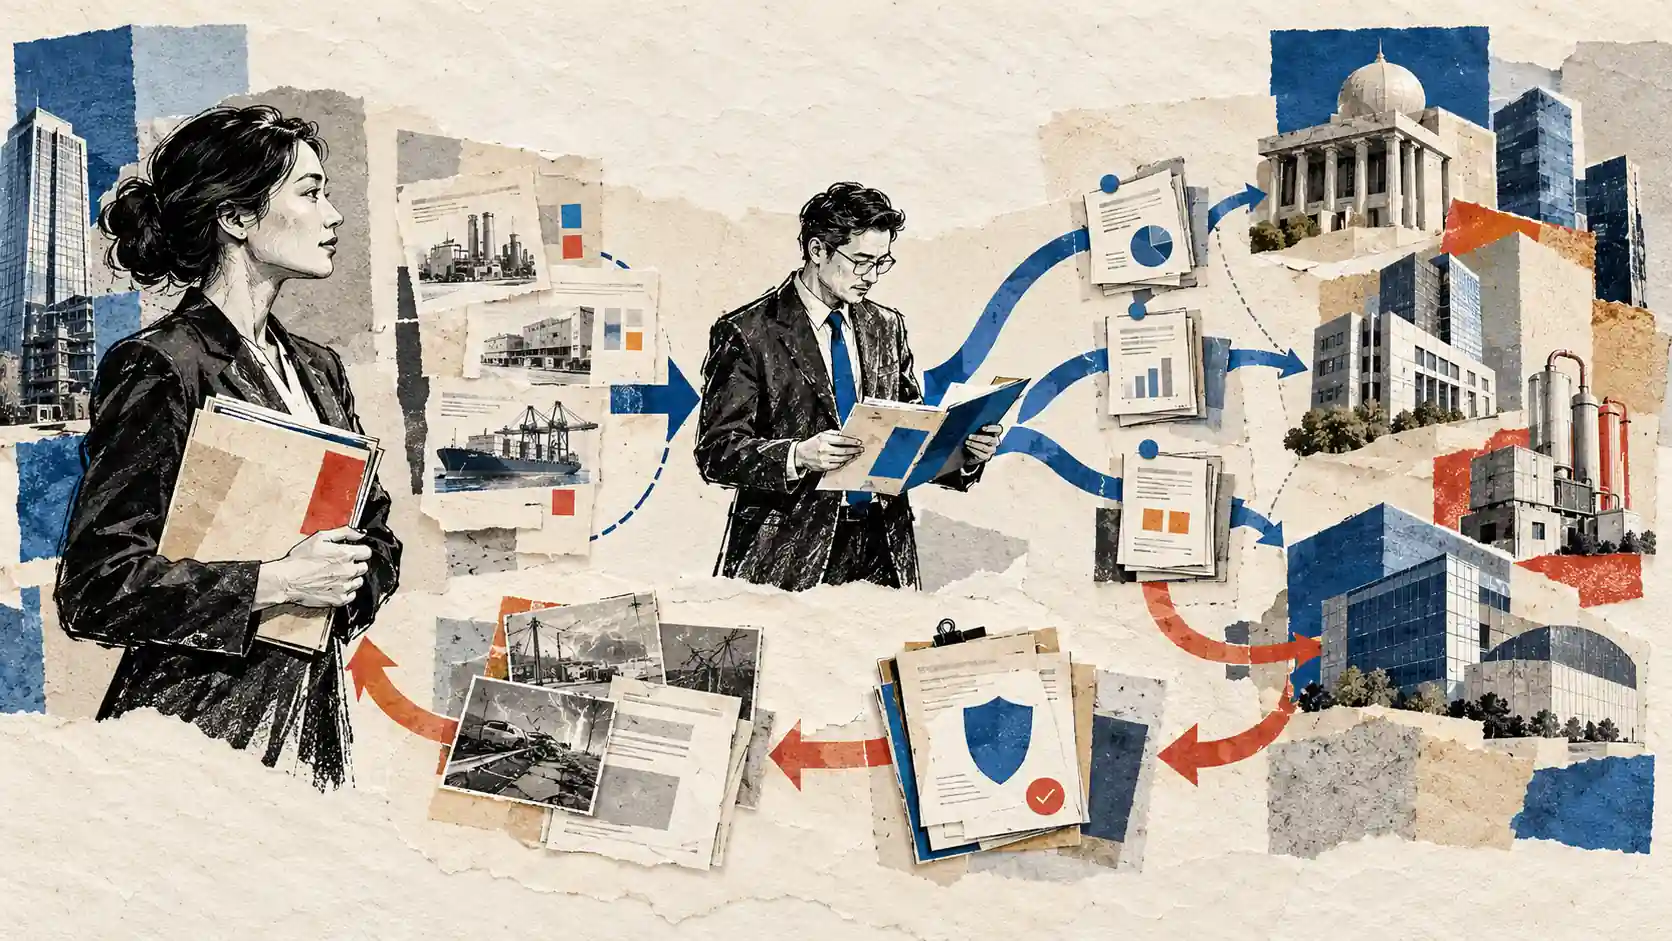
Exposure → Expected Loss → Expense → Reinsurance & Capital → Price → Terms → Claims Experience → Review
The framework is deliberately circular.
Real claims test assumptions.
New exposures change expected loss.
Terms change how losses are shared.
Reinsurance and capital affect capacity.
The next renewal then starts with better information.
This is not an actuarial pricing formula.
It is a way for business readers to understand why premium cannot be analysed independently from risk.
Risk Remains After the Negotiation
Insurance markets move through cycles.
Competition changes.
Capacity changes.
Loss experience changes.
Reinsurance costs change.
Rates can rise or fall.
Yet when the renewal negotiation ends, the factory remains in place.
The machinery keeps operating.
Vehicles remain on the road.
Cargo continues moving.
Liability continues to arise from business activity.
So when a renewal becomes cheaper, the useful question is not only:
“How much did we save?”
It is:
“Is the risk we still have being measured, understood and transferred correctly?”
Premiums can fall.
Risk does not fall simply because the quotation becomes cheaper.
- Indonesia Financial Services Authority — September 2026 Board Meeting. Used for August 2026 general insurance and reinsurance premium income of IDR99.61 trillion, a 2.35% year-on-year contraction, and aggregate RBC of 331.52%. Premium-income contraction is not treated as evidence of falling Indonesian insurance rates.
- Swiss Re Institute — World Insurance 2026. Used for global non-life market softening, 2026 real premium growth expectations, competitive pricing and inflationary pressure on claims severity. The global outlook is not assumed to describe Indonesian pricing conditions directly.
- Insurance Information Institute / NAIC Data. Used to explain loss ratios, expense ratios, combined ratios and the distinction between underwriting results and investment income.
- Editorial note: assessing pricing adequacy requires granular data by business line, exposure, claims, policy terms, expenses, reinsurance, capital and portfolio characteristics. The GATICORP framework is explanatory rather than an actuarial pricing methodology.
Published: October 23, 2026